State-level initiatives have added jurisdictional fragmentation, making it harder for multi-site operators to forecast compliance requirements; California, for example, enforces stricter standards than federal national ambient air quality standards (NAAQS), which other states can adopt under the Clean Air Act. The integration of new contaminants into core frameworks has further compounded obligations, requiring operators to navigate a broader and more technically demanding compliance set. These dynamics have coincided with persistent cost pressures. The Consumer Price Index (CPI) rose 4.2% year-over-year (YOY) in May 2026, including a 23.5% jump in energy costs, raising the operational cost of non-compliance and reinforcing the shift from one-time capital purchases toward service-intensive programs, according to the Bureau of Labor Statistics. The combination has expanded the addressable market for EHS firms and made platforms with multi-jurisdictional expertise and recurring revenue profiles attractive acquisition targets.
EHS remained a bright spot in a tepid 2025 M&A market as investors flocked to companies with steady demand not impacted by tariff noise or global geopolitical events. Services, such as consulting, training, and staffing, were particularly strong as private equity groups demonstrated strong appetite for industrial and business services. We expect 2026 to be much the same, with the potential for significant strength in EHS if the broader M&A market improves.
Chris Cardinale
Director, Capstone Partners

M&A Volume Accelerates, EHS Valuations Remain Robust
EHS acquisition activity has reversed a two-year downtrend, with 61 transactions announced or completed in year-to-date (YTD) 2026 (+15.1% YOY). While full-year 2025 deal volume represented a five-year low, improving financing conditions, stabilizing interest rates, and elevated safety services demand have contributed to rising merger and acquisition (M&A) interest in the sector to date. Additionally, EHS companies have willingly turned to asset roll-ups as a faster, more efficient alternative to expanding market share and geographic reach organically.
Increased appetite for middle market competitors with niche software offerings and strong revenue profiles has driven a three-deal uptick in private strategic M&A YOY. Public acquirer dealmaking remained flat YOY, as larger buyers have prioritized balance sheet discipline and organic growth amid lingering valuation uncertainty. Sponsor acquisitions in the sector have ticked higher, with PE platforms comprising nine deals to date (up seven deals YOY). PE add-on activity has continued to expand—up three deals to date compared to the prior year period. This follows a notable 47.9% YOY rise in 2025, when 71 sponsor-backed transactions comprised the largest share (48.3%) of sector M&A on record. The trend has suggested that financial buyers view the EHS market as a high-potential consolidation and scalable growth play.
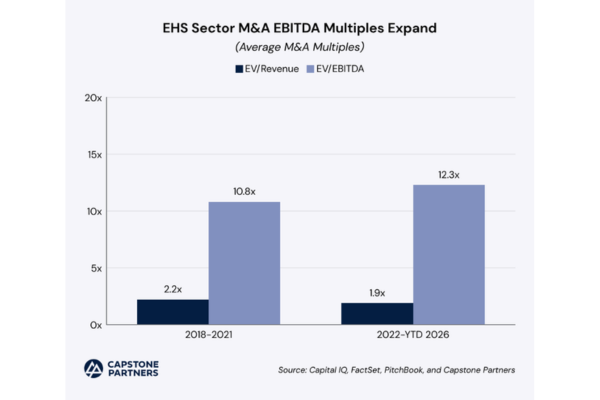
M&A multiples in the EHS sector have remained robust, averaging 12.3x EV/EBITDA between 2022–YTD 2026, outpacing the 2018–2021 average of 10.8x. This sustained expansion reflects the increasingly strategic role EHS assets play within critical infrastructure and compliance-driven value chains. By comparison, middle market Industrials valuations have remained more muted, generally trending closer to 8.6x EV/EBITDA on average between 2022-Q1 2026, underscoring the premium environment EHS assets continue to command, according to Capstone Partners’ Q1 2026 Capital Markets Update. Valuation outperformance has been most pronounced among targets with a high degree of recurring revenue, contract durability, and system interoperability, key characteristics that have continued to attract strong demand from strategic and financial buyers alike. Capstone’s Middle Market Private Equity Index Report observed a 3.8% YOY acceleration in closed middle market PE acquisitions—an improving PE backdrop that the EHS sector will likely benefit from in 2026.
PE Firms Target EHS Software and Services Platforms
PE ownership has continued to shape capital flows across the EHS sector, a trend that has anchored recent and notable platform transactions. Stable regulatory-driven demand, recurring revenue, and operational improvements have driven a growing number of EHS businesses to the market as willing buyers, which has encouraged owners to pursue sales amid resilient performance.
The growing volume of assets in market has underscored persistent sector fragmentation. EHS consulting, safety, and personal protective equipment (PPE) distribution businesses have garnered outsized financial sponsor engagement as a result. Across all segments, fragmentation has created valuation dispersion, with integrated, technology-enabled platforms commanding greater interest than collections of loosely connected EHS offerings and operations.
The above is an excerpt from Capstone Partners’ June 2026 Environmental Health and Safety Market Report. For over 20 years, Capstone Partners has been a trusted advisor to leading middle market companies, offering a fully integrated range of investment banking and financial advisory services uniquely tailored to help owners, investors, and creditors through each stage of the company's lifecycle. For more information, visit www.capstonepartners.com.